
As you might know, Banner Corporation (NASDAQ:BANR) recently reported its quarterly numbers. Revenues of US$175m were in line with forecasts, although statutory earnings per share (EPS) came in below expectations at US$1.43, missing estimates by 2.4%. Earnings are an important time for investors, as they can track a company's performance, look at what the analysts are forecasting for next year, and see if there's been a change in sentiment towards the company. So we gathered the latest post-earnings forecasts to see what estimates suggest is in store for next year.
AI is about to change healthcare. These 20 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10bn in marketcap - there is still time to get in early.
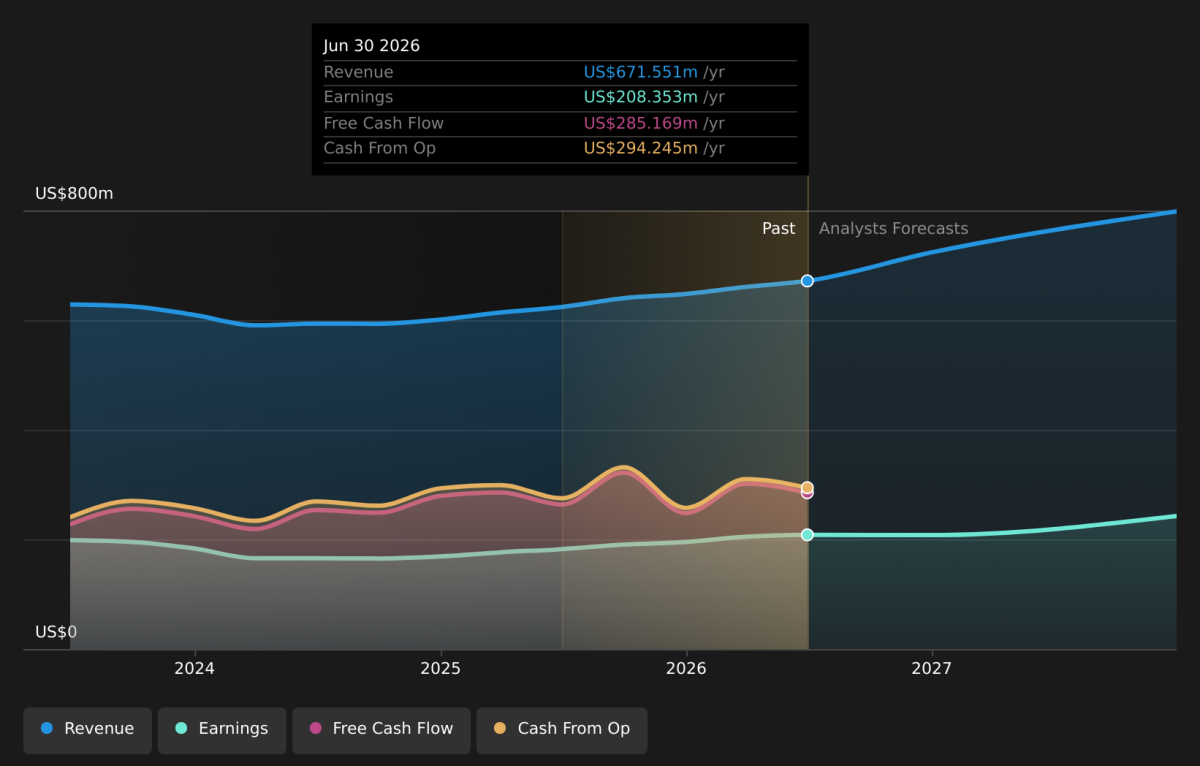
Following the latest results, Banner's five analysts are now forecasting revenues of US$723.4m in 2026. This would be a modest 7.7% improvement in revenue compared to the last 12 months. Statutory earnings per share are forecast to reduce 3.2% to US$5.93 in the same period. Before this earnings report, the analysts had been forecasting revenues of US$723.4m and earnings per share (EPS) of US$5.93 in 2026. The consensus analysts don't seem to have seen anything in these results that would have changed their view on the business, given there's been no major change to their estimates.
 The analysts reconfirmed their price target of US$76.50, showing that the business is executing well and in line with expectations. Fixating on a single price target can be unwise though, since the consensus target is effectively the average of analyst price targets. As a result, some investors like to look at the range of estimates to see if there are any diverging opinions on the company's valuation. There are some variant perceptions on Banner, with the most bullish analyst valuing it at US$81.00 and the most bearish at US$73.00 per share. Still, with such a tight range of estimates, it suggeststhe analysts have a pretty good idea of what they think the company is worth.
Taking a look at the bigger picture now, one of the ways we can understand these forecasts is to see how they compare to both past performance and industry growth estimates. The analysts are definitely expecting Banner's growth to accelerate, with the forecast 16% annualised growth to the end of 2026 ranking favourably alongside historical growth of 1.1% per annum over the past five years. Compare this with other companies in the same industry, which are forecast to grow their revenue 7.8% annually. It seems obvious that, while the growth outlook is brighter than the recent past, the analysts also expect Banner to grow faster than the wider industry.
The Bottom Line
The most obvious conclusion is that there's been no major change in the business' prospects in recent times, with the analysts holding their earnings forecasts steady, in line with previous estimates. Happily, there were no major changes to revenue forecasts, with the business still expected to grow faster than the wider industry. There was no real change to the consensus price target, suggesting that the intrinsic value of the business has not undergone any major changes with the latest estimates.
With that in mind, we wouldn't be too quick to come to a conclusion on Banner. Long-term earnings power is much more important than next year's profits. We have forecasts for Banner going out to 2027, and you can see them free on our platform here.
It is also worth noting that we have found 1 warning sign for Banner that you need to take into consideration.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.